All Categories
Featured
Benefits of Whole Life Insurance to Protect Families
How to Navigate 2026 Health Insurance Enrollment Successf...
Navigating EPO Networks for Better Family Health Coverage
The Power of Permanent Life Insurance for Rancho Santa Ma...

Benefits of Whole Life Insurance to Protect Families
Table of Contents
HHS prepares to broaden access to disastrous health protection through its brand-new hardship exemption guidance, the department revealed today.
HHS' brand-new challenge exemption guidance will make it much easier for individuals to access disastrous protection if they are ineligible for advance payments of the superior tax credit (APTC) or cost-sharing decreases (CSRs), based upon their yearly home earnings. Usually, consumers who are newly ineligible for APTC or CSRs due to their forecasted yearly income being below 100% or above 400% of the federal poverty line are eligible for a hardship exemption and can enroll in devastating protection.
The changes were driven by forecasted increases in medical insurance premiums for the 2026 plan year throughout the specific market, CMS said in an accompanying fact sheet. Rate boosts could lead to challenges with acquiring protection under a Qualified Health insurance, especially for those whose earnings makes them ineligible to receive APTC or CSRs.
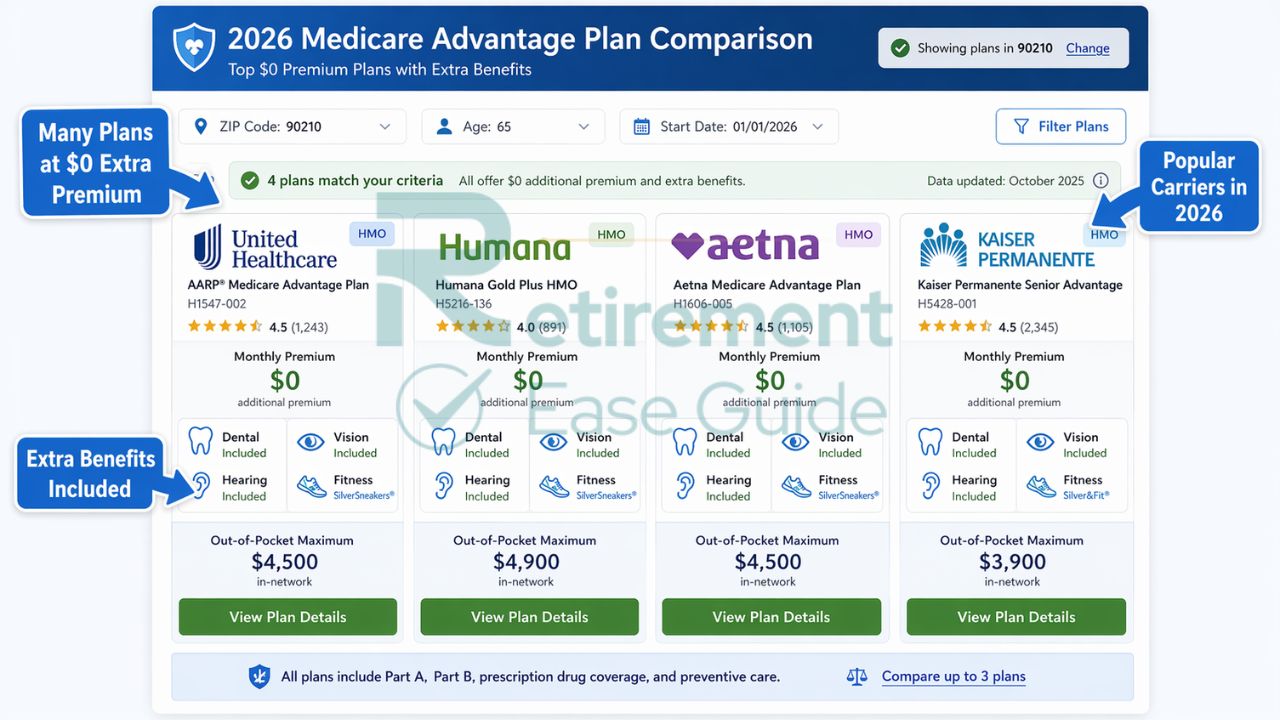
Insurance in Buena Park CATop 2026 Medicare Advantage Plans
"Catastrophic protection uses cost effective health insurance coverage for more youthful Americans and those facing challenge to have security when they need it most," HHS Secretary Robert F. Kennedy, Jr. said in the statement. "Expanding access to devastating protection is another action in making health insurance more cost effective, building on the development made because the passage of President Trump's One Big Beautiful Expense.".
NAIFA has actually long advocated for access to affordable devastating health strategy alternatives. Under the brand-new policy, consumers who are not qualified for advance payments of premium tax credits or cost-sharing reductions on the Health Insurance Market are eligible for difficulty exemptions enabling them to acquire catastrophic strategies beginning November 1.
They likewise cover preventative services needed under the Affordable Care Act and approximately 3 pre-deductible gos to with medical care doctors. The exemption will use to customers purchasing plans either on or off the Exchange. Beginning November 1, 2025, consumers can make an application for the challenge exemption in 2 methods: Use online for Marketplace protection on or through a qualified partner.
Send a hardship exemption form by mail. HHS is also streamlining the process by improving the review of paper applications to minimize the administrative problem on customers. This modification will make it much easier for individuals experiencing difficulty and looking for a devastating strategy to access the complete series of devastating protection options readily available to them.
Optimizing Medicare Part D Coverage for 2026
Pennsylvania family health insurance coverage for 2026 operates on 2 parallel tracks that often apply at the same time to homes with children. The Pennie market covers adults and household systems with federal premium tax credits and Silver cost-sharing reductions. Pennsylvania CHIP covers children under 19 in families earning as much as 319 percent of the federal poverty level around $102,521 for a family of 4 through a separate, typically more detailed and cheaper program.
Comprehending both tracks is the essential to discovering the lowest overall family coverage expense in 2026. Mixed-race household of 4 at a Bethlehem kitchen table reviewing 2026 Pennsylvania household health insurance and CHIP choices Pennsylvania CHIP covers children under 19 in homes making approximately 319 percent of the federal poverty line around $102,521 for a household of four in 2026.
CHIP Tier Income Variety (Family of 4) Regular Monthly Premium Copays Medical Assistance (kids)Under $54,395 (under 215% FPL)$0None Free CHIP$ 54,395$66,120 (215%258% FPL)$0Minimal ($5$10) Low-Cost CHIP$ 66,120$89,750 (258%350% FPL)$30$75/child/mo$10$20 per check out Full-Cost CHIP$ 89,750$102,521 (350%319%?
Exploring Indexed Universal Life Policies During Retirement
Pennsylvania CHIP is administered through 7 handled care carriers, each covering specific counties. Carrier accessibility determines which CHIP strategy a household chooses not all CHIP providers run statewide. At registration, the Pennie or COMPASS system presents the CHIP providers offered at the family's address. Families then pick their favored CHIP provider for each qualified kid, and the provider manages all strategy benefits, permissions, and customer care for that kid.
An Independence Blue Cross Pennie prepare for moms and dads combined with Self-reliance Blue Cross CHIP for kids produces a constant supplier network and reduces coordination intricacy. When possible at the same premium level, matching CHIP and Pennie providers within a household simplifies supplier choice for kids's specialists who accept both programs.

Latest Posts
Benefits of Whole Life Insurance to Protect Families
How to Navigate 2026 Health Insurance Enrollment Successfully
Navigating EPO Networks for Better Family Health Coverage